
The Fed Held Rates Steady Again — So Why Didn’t Mortgage Rates Drop?
I hear this question all the time: “Shouldn’t I just wait until the Fed cuts rates?” It’s a fair question, and with the Fed’s latest decision back in the news, I want to clear up a misunderstanding I see trip up a lot of buyers and sellers here in Greater Houston.
Where Things Stand Right Now
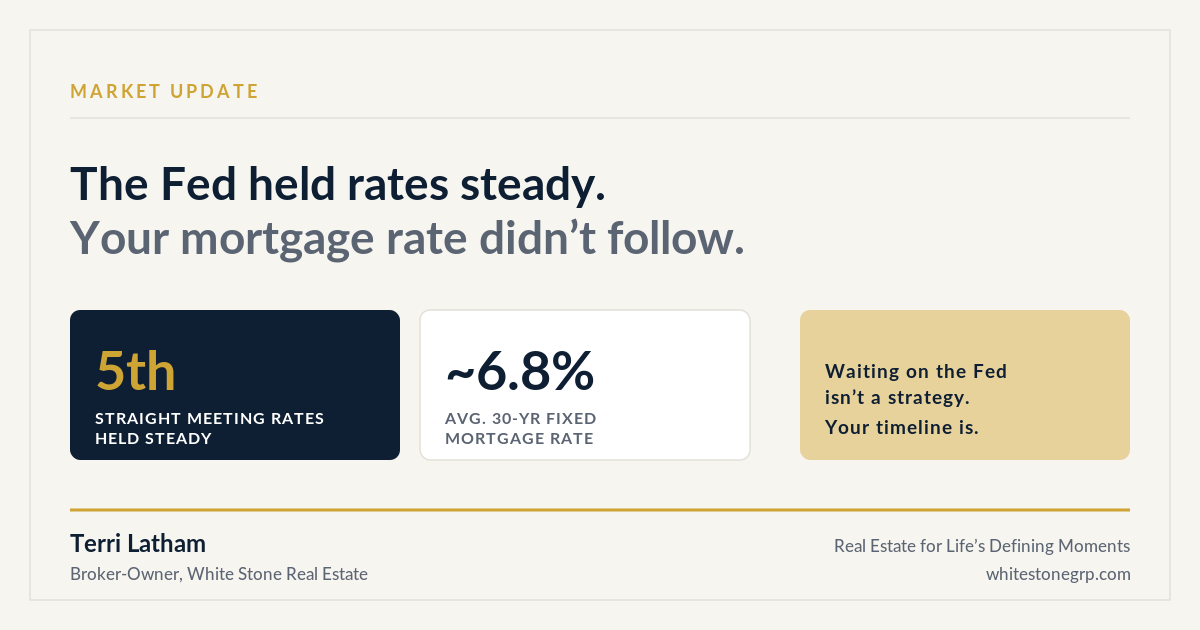
The Federal Open Market Committee voted to hold its benchmark rate steady for the fifth consecutive meeting, keeping the federal funds rate in the same target range it’s held for months. Notably, this wasn’t a unanimous decision this time — a few policymakers actually pushed for a hike, a sign the Fed isn’t in any rush to make borrowing cheaper. Meanwhile, the average 30-year fixed mortgage rate has stayed in the mid-to-high 6% range, and most forecasts have it hovering around there for the rest of the year rather than dropping meaningfully.
Why “Waiting for the Fed” Isn’t a Strategy
Here’s the part that surprises people: the Fed’s rate and your mortgage rate are not the same thing, and they don’t move in lockstep. Mortgage rates respond more to inflation expectations, the bond market, and global events than to the Fed’s short-term rate directly. That’s why we’ve seen mortgage rates move up and down in recent weeks even while the Fed itself hasn’t budged. Betting your home search on a Fed cut that may or may not translate into meaningfully lower mortgage rates — and may not even happen this year — is a plan built on a coin flip.
What This Means If You’re Buying
If a home works for your life and your budget today, “the rate might improve someday” usually isn’t a strong enough reason to wait. Rates can always be refinanced later if they drop; the home you love, at the price it’s listed today, might not still be there. I’d rather walk you through real numbers for your specific situation than have you chase a hypothetical.
What This Means If You’re Selling
Stable-but-elevated rates mean today’s buyers are serious — they’ve already made peace with the current rate environment and are shopping with real intent, not waiting for a discount that may not come. That’s good news for a well-priced, well-presented listing.
So, What Should You Actually Do?
Stop watching the Fed calendar and start looking at your own calendar — your timeline, your goals, your life. The rate environment right now is workable. It rewards people who plan around their own situation instead of waiting on a headline.
Wondering What Today’s Rates Mean for You?
I’d love to walk you through what today’s market means for your specific situation — no pressure, just real numbers. Reach out and let’s talk about your next move.